My first mortgage. A little clearer.
Walk from the first idea to moving day with Puppet Jack. Scroll gently, or use Next to take it one scene at a time.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Let’s open the door.
You can start the conversation while you are saving, looking at homes or simply working out what to do next.
What does home mean to you?
Think about the space, location and everyday costs that fit your life. A clear wish list gives the budget a purpose.
Start at the kitchen table.
Bring together your income, spending, existing commitments and savings. Your monthly comfort matters as well as the purchase price.
Leave room for real life.
Look beyond the mortgage payment. Household bills, repairs and the money you want left each month belong in the plan too.
The deposit is one part.
Keep buying fees, moving costs and any applicable property tax in view. Explain where your deposit comes from, including any family help.
Build a clear picture.
Gather income, spending and deposit evidence. The documents needed depend on your circumstances and the application.
Keep the detail together.
Check that the information tells a consistent story. Agree a secure route with Jack before sharing identity documents, statements or other sensitive records.
Understand an agreement in principle.
It indicates what a lender might lend. It is not a mortgage offer or a guarantee: the full application and property still need assessment.
Could this be your home?
Take your budget and questions with you. Look at how the home works for your everyday needs, as well as how it feels.
Ask about the details.
Consider condition, tenure, what is included in the sale and ongoing costs. Note questions to investigate rather than assuming everything is settled.
A decision, with checks still ahead.
For an ordinary purchase in England and Wales, an accepted offer is not legally binding until contracts are exchanged. Your solicitor explains the commitment.
Bring the checks together.
The lender assesses your application and the property. Mortgage, legal and property work can progress alongside one another; the stages can overlap.
A valuation is not your survey.
The lender’s valuation serves its lending assessment. A separate survey helps you understand the condition of the home you are considering.
Resolve the remaining questions.
Review the mortgage offer, its conditions and the legal position with your advisers. In England and Wales, exchange makes the purchase legally binding.
The move becomes real.
Once the agreed completion arrangements are in place, your solicitor transfers the funds and the keys can be released. Confirm the details with your advisers.
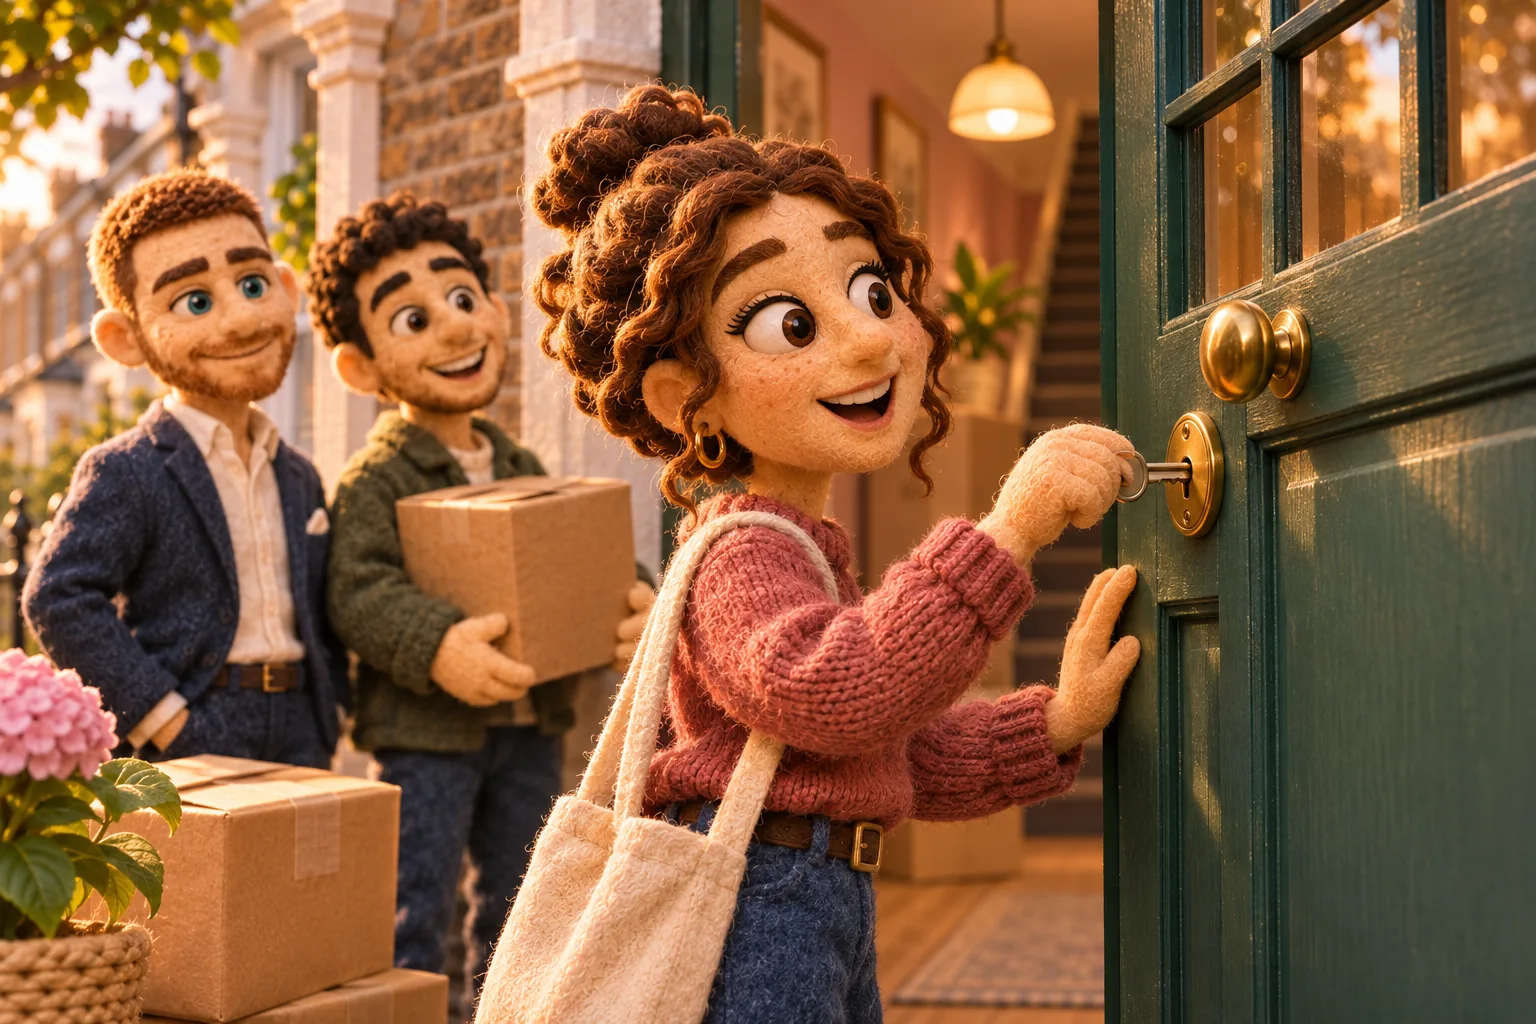
Your own front door.
Keep the practical arrangements close: key collection, moving plans, utilities and the insurance cover agreed for your purchase.
Make yourself at home.
Note your first mortgage payment, keep your household budget under review and ask for help if your circumstances change.
You don’t need every answer.
Just your first question.
Saving, viewing or ready to make an offer? Tell Jack where you are and what you have in mind.
Prefer to call? 07456 935677 · Email Jack
Your home may be repossessed if you do not keep up repayments on your mortgage.
Fees, service scope and complaints · Explore the detailed journey
About this illustrated guide and its sources
A general first-home overview for a standard purchase in England and Wales. Stages can overlap and the process differs elsewhere in the UK. It is not an eligibility decision, mortgage offer or promised timetable. Ask the appointed professionals about your own purchase.
All Puppet Jack images and animated scenes are AI-generated illustrations. The buyers and situations are fictional; they do not show completed client transactions. General overview based on the official sources below, checked on 20 November 2026.